
The New Industrial Frontier: why now is the time to invest in technologies transforming industry
AI, robotics, energy security and industrial innovation are converging, creating a multi-trillion-dollar opportunity to rebuild industry.
We believe now is the time to invest in technologies transforming the world's critical industries.
Demand for these solutions is growing more urgent, driven by energy security, rising costs, supply chain resilience and industrial productivity, as much as decarbonisation. At the same time, much of venture capital is concentrating on AI and a small number of high-profile companies, creating more attractive conditions for disciplined investors in industrial technology.
Three structural forces are driving this opportunity.
1. Geopolitics is accelerating the transformation of energy and supply chains
Recent geopolitical disruptions, from Russia and Ukraine to the Middle East conflict, have exposed the vulnerability of global energy and supply chains, and the past 12 months have made this acute. Australia imports approximately 90% of its jet fuel, while China dominates substantial parts of the battery and critical minerals supply chain. Energy security and domestic industrial capabilities have consequently become strategic priorities.
Governments and corporates are responding by investing in local production, diversifying supply chains and looking for technologies that improve productivity and reduce reliance on imported energy and materials. Australia's $1.1 billion Cleaner Fuels Program is one example, supporting domestic production of low-carbon liquid fuels while strengthening fuel security. Climate benefits remain important, but the key drivers are cost, security of supply and competitiveness.
2. AI and robotics are transforming the physical economy
AI is attracting extraordinary amounts of capital, with the largest hyperscalers alone spending around US$700 billion this year1. But some of the most interesting and financially compelling opportunities lie in its application to the physical world.
AI, robotics, automation and advanced software are creating new ways to improve the productivity of energy networks, transport fleets, industrial facilities and mining operations. We look for startups applying these technologies to major industrial problems, including:
- AI and industrial software to optimise electricity networks, energy consumption, transport operations and industrial processes.
- Robotics and autonomous systems to inspect, maintain and operate physical assets more efficiently.
- Advanced sensing, computer vision and analytics to improve asset performance, identify defects and reduce operating costs.
- Industrial and materials technologies that improve resource recovery, reduce energy consumption and make existing processes more efficient.
Our portfolio company Hullbot is one example. Its at the intersection of AI and robotics. Hullbot’s autonomous robots clean vessel hulls, reducing fuel burn by 15%. They have over 50 bots deployed around the world and have completed over 2,500 vessel cleans translating to companies saving over 3.2 million liters of fuel.
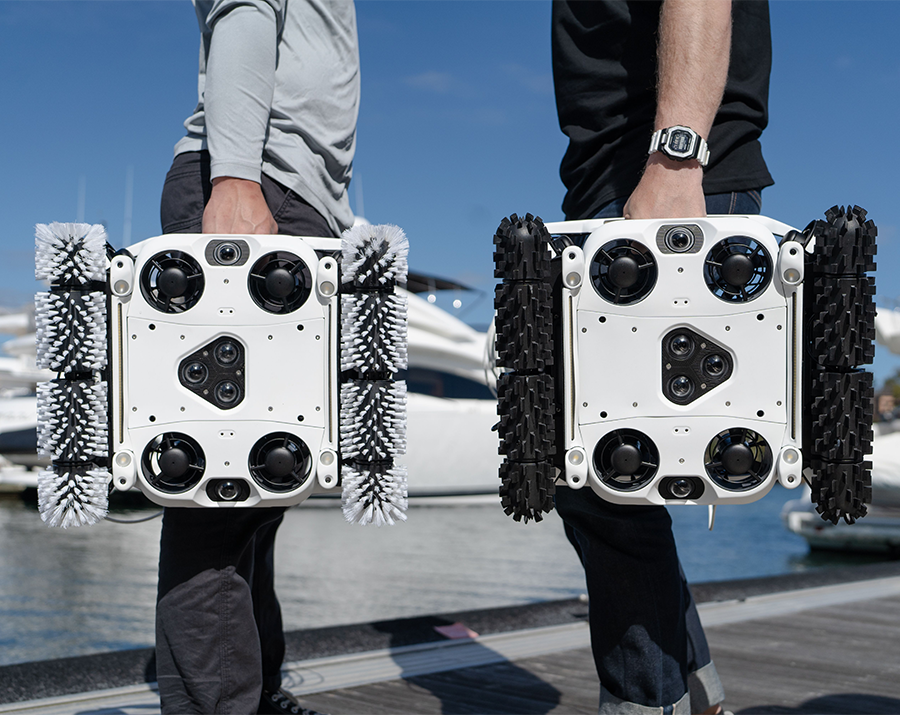
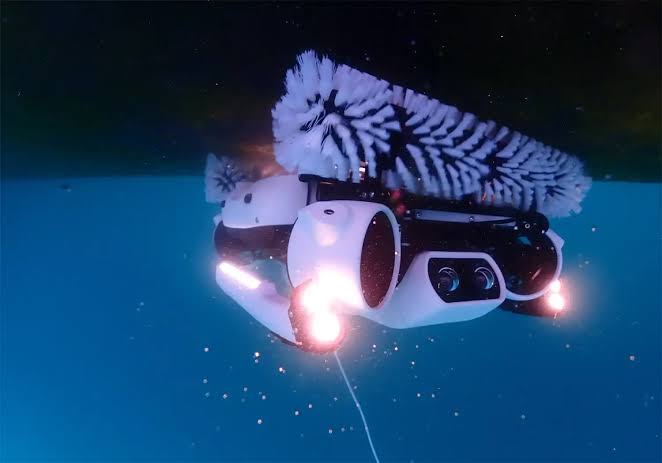
Hullbot’s portable cleaning robots with interchangeable brushes (left) and at work underwater (right).
AI is also creating demand for more energy infrastructure. AEMO forecasts that data centres could increase their share of electricity supplied through Australia's National Electricity Market from approximately 3% today to 13% by 2035–36. That growth creates investment opportunities in grid optimisation, energy management, storage and technologies that increase the capacity and efficiency of existing infrastructure.
Importantly, industrial applications of AI also offer defensibility that is difficult to replicate. While AI may make software development faster and cheaper, replicating a proven industrial solution requires more than code. Proprietary operating data, integration with physical systems, customer relationships, regulatory approvals and real-world performance can create significant barriers to entry.
3. The investment environment is becoming more attractive for specialist investors
The underlying demand for technologies reshaping industry is growing, but the venture capital market has changed considerably. During the 2021–22 investment boom, abundant capital drove valuations higher, often before companies had demonstrated commercial viability. Today, investors are placing much greater emphasis on customer demand, revenues, capital efficiency and credible pathways to scale.
Capital has also become increasingly concentrated. According to Currence, a specialist energy market intelligence provider, venture investment in the sector reached US$26.1 billion in the first half of 2026, up 55% year-on-year, but deal count fell 25% and the ten largest transactions took 42% of total funding. Capital is increasingly concentrated in fewer, larger transactions. We believe this creates opportunities for specialist investors in less crowded segments of the Series A market.
That can translate into more attractive entry valuations and investment terms. At the same time, companies increasingly need to demonstrate genuine customer demand and a disciplined approach to deploying capital.
Exit pathways are opening too. H1 2026 was a record half for exits in the sector, with 152 completed and 89% of them acquisitions, largely by incumbents buying proven technology2.
Of course, a more selective market creates challenges, particularly for capital-intensive businesses requiring substantial follow-on funding. The ability to assess commercial potential, technology risk and future financing requirements has therefore become more important than ever.
At Climate Tech Partners, we see the most compelling opportunities where new technologies address significant problems for major industrial businesses. Our investment model is built around close collaboration with corporate partners such as Qantas, Airbus, BHP Ventures and Ausgrid. These relationships help us identify commercial challenges, source relevant startups and assess whether emerging technologies can deliver meaningful value. They can also help portfolio companies access customers, technical expertise and commercial partnerships, with the same kind of incumbents now driving most exits.
Our focus is on backing the technologies that will make the world's critical industries more productive, competitive and resilient. The scale of the opportunity is enormous, and the time to invest is now.
Source
(1) https://www.tmtfinance.com/insights/2026-hyperscaler-capex-tops-us700bn-analysis-2/
(2) Currence, 2026 First Half climate tech investment trends report (https://www.currence.ai/request-report?report-id=h1_26_investment_report)
Latest articles
Noga Edelstein has seen deals from every side of the table: as the lawyer who documented them, the founder who needed them and the investor who sources and decides them.

